

Becoming self-employed in Spain: key points
- Becoming self-employed in Spain means registering as an autónomo, the Spanish status for independent contractors and freelancers.
- Applicants need a NIE and a Spanish bank account before registration, and non-EU nationals also need a residence permit that allows self-employment.
- Registration involves two separate filings: the census registration with the AEAT on Modelo 036 (Modelo 037 was abolished on 3 February 2025) and the alta in the RETA with Seguridad Social, which self-employed workers must complete electronically.
- For 2026, autónomo contributions follow 15 net-income brackets, from €205.88 a month at the lowest minimum base to €607.35 a month at the minimum base of the top bracket.
- The tarifa plana reduces contributions for the first 12 months and can extend to 24 months if net income stays below the annual SMI, but the €80 amount is confirmed only for 2023 to 2025 and the 2026 amount needs checking.
- Autónomos file quarterly IRPF and VAT returns via Modelo 130 and Modelo 303, plus the annual Modelo 100.
- Services invoiced to a business client in the UK or the US are generally not subject to Spanish VAT, while a business client in another EU country accounts for the VAT itself under the reverse-charge rule.
Why the autónomo route matters for foreign entrepreneurs
Spain lets foreign professionals work for their own account under the autónomo regime.
Becoming self-employed in Spain gives professionals access to the Spanish market and to a reduced contribution during the first months of activity.
This guide sets out every step of becoming self-employed in Spain in 2026, from the initial NIE application to the first quarterly tax return.
What is an autónomo?
An autónomo is a physical person carrying out an economic activity for their own account, without an employment contract.
The status does not separate personal and professional assets, which means the autónomo remains personally liable for business debts.
The category is used across sectors as varied as tourism, digital consulting, education, hospitality and retail, and it remains the fastest route to independent work in Spain.
Many French, British and Dutch nationals choose becoming self-employed in Spain because of the country’s proximity, quality of life and progressive social security regime.
Prerequisites for foreign applicants
Non-Spanish nationals can obtain autónomo status subject to a small set of prerequisites.
- Tax residence in Spain: under article 9 of the personal income tax law you are tax resident in Spain when you spend more than 183 days in a calendar year in Spain or when the main base of your activities or economic interests is here.
- Foreigner’s Identification Number (NIE): the NIE is mandatory for every administrative step in Spain, from opening a bank account to registering with the AEAT. Our guide to obtaining an NIE in Spain covers the application in detail.
- Spanish bank account: a Spanish IBAN is required to receive client payments and to pay social security contributions by direct debit, as explained in our guide to opening a Spanish bank account as a non-resident.
- Residence and work authorisation: non-EU nationals must hold a valid residence permit, typically obtained through the digital nomad visa or the startup visa.
Becoming self-employed in Spain without meeting these prerequisites triggers penalties and delays that are best avoided.
Declaring your activity to the Hacienda
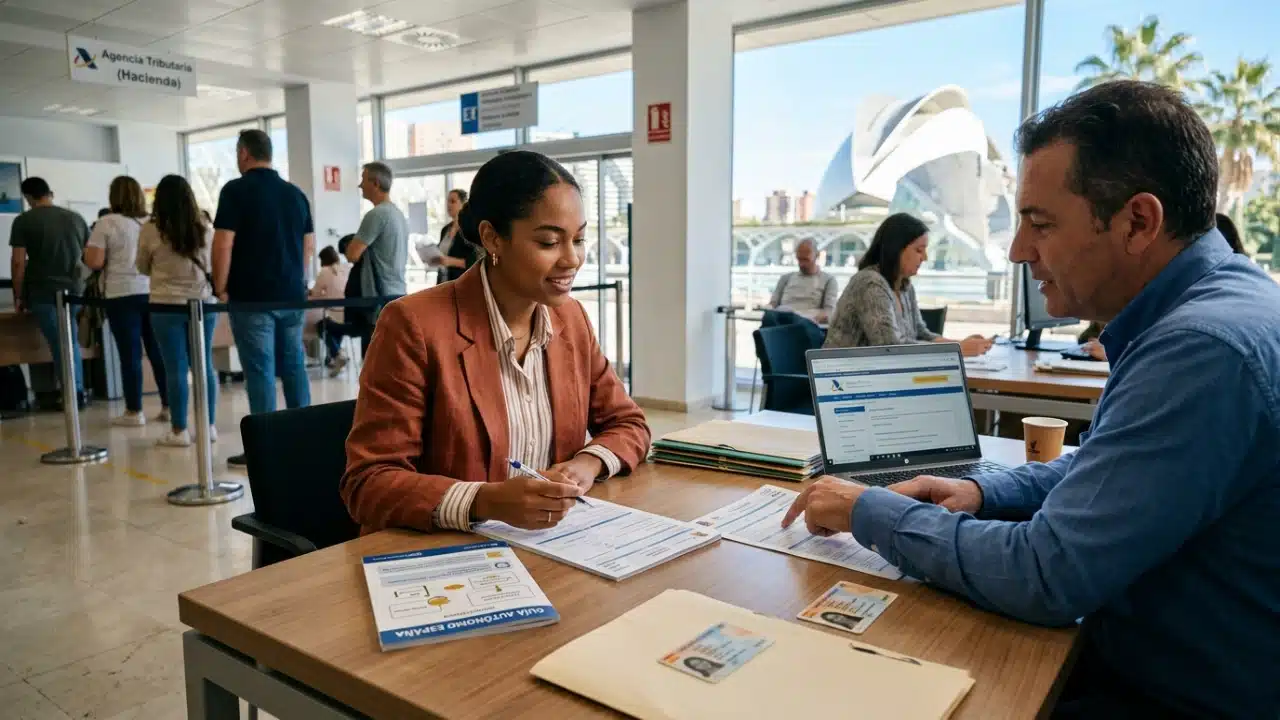
The Agencia Tributaria, commonly known as Hacienda, is the Spanish tax authority responsible for managing income tax, VAT and every tax filing.
The first step in becoming self-employed in Spain is to declare your activity to Hacienda through the tax census.
Applications can be filed online through the AEAT electronic office, but many foreign applicants prefer an in-person appointment to confirm the correct classification of their activity.
The census filing uses Modelo 036. The AEAT abolished the simplified Modelo 037 through Orden HAC/1526/2024, in force since 3 February 2025, so freelancers now use Modelo 036 as well.
The correct economic activity code is selected from the official IAE Epigraphs list, and it affects the VAT regime that applies to you.
Autónomos providing services to clients in other EU countries must also register in the Registro de Operadores Intracomunitarios (ROI) and obtain a VIES number, as detailed in our note on VAT registration in Spain for foreign businesses.
Registering with Seguridad Social
Once the census filing is complete, the next step in becoming self-employed in Spain is registration with Seguridad Social.
Self-employed workers must handle registration, contributions and notifications with Seguridad Social electronically, a duty in force since 1 October 2018. The alta is requested in the Seguridad Social electronic office with a digital certificate, an electronic DNI or Cl@ve.
On completion, the applicant receives a Social Security number and is enrolled in the Régimen Especial de Trabajadores Autónomos (RETA), the special contribution scheme for the self-employed.
Applicants without a Spanish digital certificate should first read our note on the Spanish digital certificate and Cl@ve platform, which speeds up almost every step.
Autónomo contributions in 2026
Since 2023, autónomo contributions follow a progressive net-income model with 15 income brackets, three in the reduced table and twelve in the general table.
For 2026, Real Decreto-ley 3/2026 (article 3.4) keeps the 2025 tables in force until a new budget law replaces them, and Orden PJC/297/2026 sets the 2026 bases and rates. The combined rate is 31.50%: 28.30% for common contingencies, 1.30% for professional contingencies, 0.90% for cessation of activity, 0.10% for vocational training and 0.90% for the intergenerational equity mechanism.
| Bracket | Monthly net income | Minimum base | Monthly contribution at the minimum base |
|---|---|---|---|
| Reduced table, bracket 1 | Up to €670 | €653.59 | €205.88 |
| General table, bracket 12 | Above €6,000 | €1,928.10 | €607.35 |
You can choose a higher base within the limits of your bracket, and the full tables with the minimum and maximum base of each bracket are in the Orden.
The tarifa plana is a reduced contribution for people who register for the first time or who were not registered in the previous two years. Article 38 ter of the Self-Employed Workers’ Statute (Ley 20/2007) provides a reduced quota for the first 12 complete calendar months and, if net income stays below the annual SMI, for a further 12 months. The amount is set by the budget law, and the BOE text records €80 a month for 2023 to 2025 only.
The 2026 amount is therefore not confirmed as at 6 October 2026. Contact us before your alta to confirm the amount that applies to your start date.
Ongoing obligations of an autónomo
Autónomos are responsible for two main taxes:
- Personal Income Tax (IRPF): a progressive tax on annual earnings, with rates that vary by autonomous community. Autónomos file quarterly payments on account via Modelo 130 and reconcile through the annual Modelo 100.
- Value Added Tax (VAT): a consumption tax at the standard rate of 21%, filed quarterly through Modelo 303 and reconciled annually through Modelo 390.
Autónomos must issue compliant invoices, keep their accounting records and observe every filing deadline set out in our guide to Spanish tax deadlines.
On retention, the tax authority’s right to assess a tax year expires after four years under article 66 of the General Tax Law, while article 30 of the Commercial Code requires businesses to keep their books and supporting documents for six years from the last entry. Ask us which period applies to your activity.
Ongoing compliance is where most foreign professionals underestimate the demands of becoming self-employed in Spain, and where specialist support delivers the biggest return.
Autónomos should also familiarise themselves with their entitlements to sick leave, parental leave and cessation of activity, covered in our note on autónomo rights in Spain in 2026.
Becoming self-employed in Spain with US or UK clients
This section covers Spanish rules only. Coordinate your US or UK tax filings and any home-country social security position with your home-country adviser.
Invoicing clients outside Spain: VAT
Article 69 of the Spanish VAT law treats a service to a business customer as supplied in Spain when the customer’s business is established in Spain, subject to the special rules in articles 70 and 72. A service invoiced to a business client in the UK or the US is therefore generally outside Spanish VAT, so Spanish VAT is not charged on that invoice.
For a business client in another EU country, the client is the taxable person and accounts for the VAT itself, under the reverse-charge mechanism. Article 6.1.m of the invoicing regulation (Real Decreto 1619/2012) requires the invoice to carry the words «inversión del sujeto pasivo» when the customer is the taxable person. The AEAT guidance on identification for operations with other EU businesses explains the ROI registration and the Modelo 349 statement.
The ROI and Modelo 349 relate to operations with other EU Member States, and the UK has not been a Member State since Brexit. Private customers outside the EU follow a different rule: article 69 lists services such as advertising, consultancy, legal and accounting services, data processing and translation as not supplied in Spain when the recipient is not a business and is established outside the EU. Other services to consumers need a case-by-case check, so contact us before you invoice consumers abroad.
Contributions and the tarifa plana
The 2026 contribution tables and the position on the tarifa plana are set out in the section on autónomo contributions above. The 2026 amount of the reduced contribution is not confirmed, so ask us before you plan your first-year cash flow.
Social security coordination with the US and the UK
The US-Spain social security agreement, known as a totalisation agreement and in force since 1 April 1988, covers social security contributions and benefits, not income tax. Article 4 provides:
A person who would otherwise be covered under the laws of both Contracting States with respect to self-employment shall be subject to the laws of only the Contracting State of which he is a resident.
The US Social Security Administration summary adds that a worker who is normally self-employed in one country and transfers the business to the other for five years or fewer stays covered in the country of origin. It also says that Spanish periods count towards a US benefit only if you have at least six US credits, and that US periods count towards a Spanish benefit only if you have at least one year of coverage in the Spanish system.
For British freelancers, article SSC.10(3)(a) of the Protocol on Social Security Coordination in the UK-EU Trade and Cooperation Agreement provides:
a person pursuing an activity as an employed or self-employed person in a State shall be subject to the legislation of that State;
Article SSC.7 of the same Protocol requires a State, to the extent necessary, to take into account periods of insurance, employment, self-employment or residence completed in another State when its own rules make a benefit conditional on completing periods. People who were already in a cross-border situation between the UK and an EU Member State at the end of the transition period can remain covered under article 30 of the Withdrawal Agreement for as long as that situation continues without interruption.
Whether your US or UK periods count towards a future pension, and whether you need a certificate of coverage, depends on your history and dates. Contact Félix Delaguía at felix.delaguia@delaguialuzon.com or on +34 963 74 16 57 to confirm your case.
Tax residence and Modelo 720
Registering as an autónomo and working from Spain usually brings you within the Spanish tax residence tests described above, and a tax resident is taxed in Spain on worldwide income. Our guide to UK Spain double taxation explains the 183-day rule and residence certificates.
Tax residents who hold accounts, securities or property abroad must also report them on the Modelo 720 once a category exceeds €50,000, between 1 January and 31 March of the following year, under the general tax procedures regulation, and the AEAT filing page gives the dates for each campaign. Read our guide to the Modelo 720 before your first return, and our note on social security for cross-border teleworkers if you also work remotely for a foreign employer.
Common mistakes when becoming self-employed in Spain
- Starting activity before completing the RETA registration, which triggers backdated contributions and penalties.
- Selecting the wrong IAE code, which affects VAT treatment and future tax deductions.
- Missing the quarterly Modelo 303 or 130 deadlines: a return filed late without a prior request from the tax office carries a surcharge of 1% plus 1% for each complete month of delay, rising to 15% after 12 months (article 27 of the General Tax Law).
- Ignoring intra-EU VAT rules and failing to register on the VIES database.
- Underestimating the transition from the tarifa plana to standard bracket contributions.
- Attempting to register without a Spanish digital certificate, which slows every subsequent filing.
Founders who quickly outgrow the autónomo threshold should also review our comparison of SL versus self-employed in Spain to decide when incorporation makes better sense.
Ready to become autónomo in Spain?
Contact our legal team for personalised guidance on your case.
Email: felix.delaguia@delaguialuzon.com
Phone: +34 963 74 16 57
Office: Avinguda Regne de Valencia, 6, 1º-2º, 46005 Valencia


