Spanish wealth tax: key points
- The Spanish wealth tax is based on the net value of your assets on 31 December each year, not on your annual earnings.
- Passive income, such as interest, dividends, capital gains and rental income, is taxed separately under Spain’s personal income tax or non-resident tax rules.
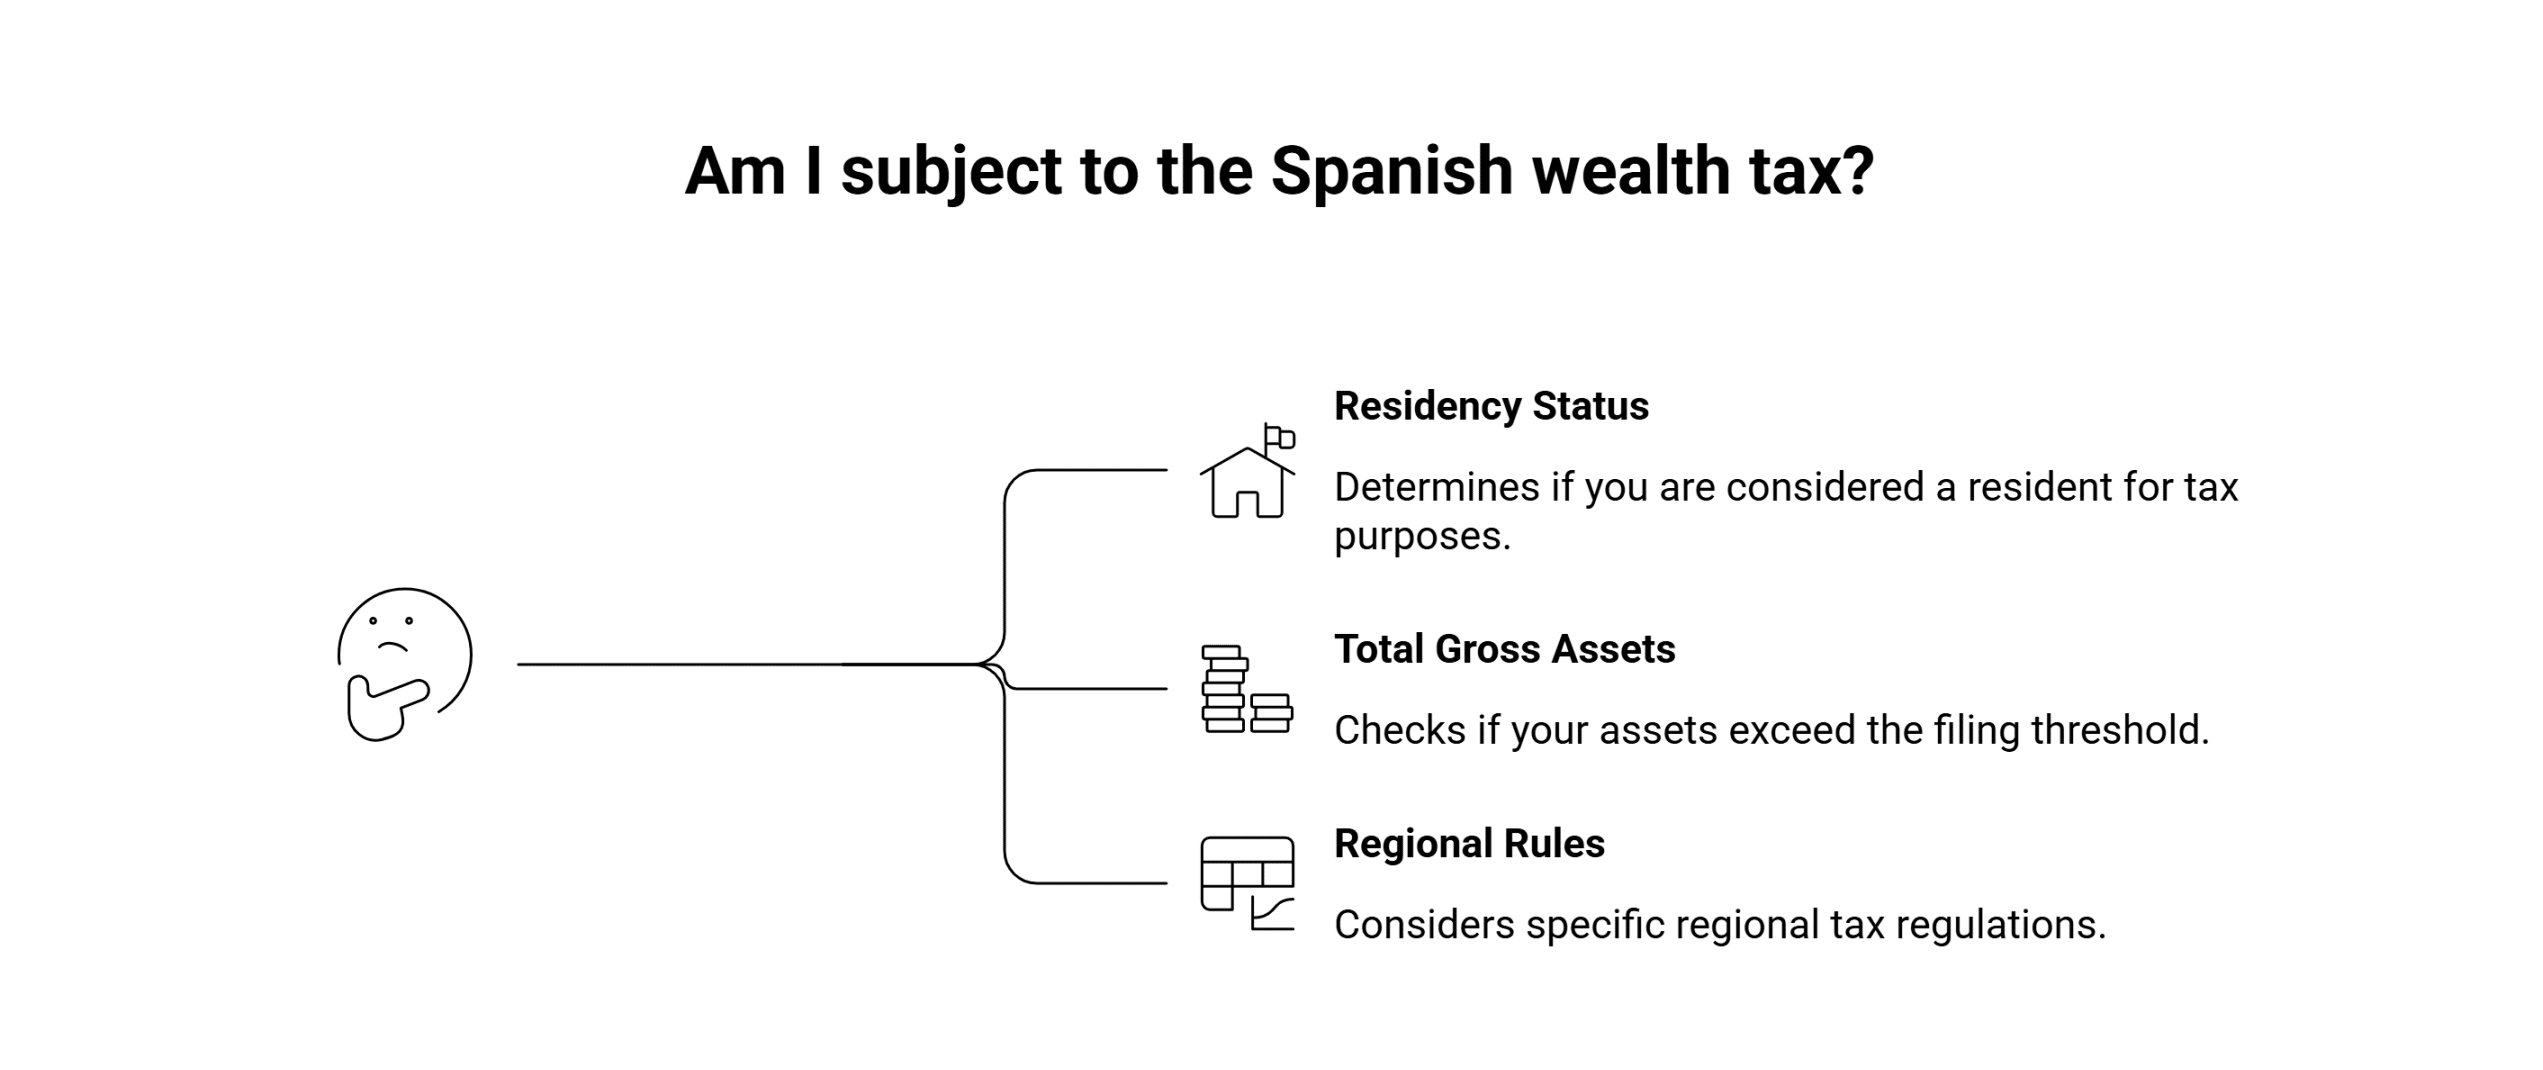
- Tax residency status determines whether you are taxed on worldwide assets and income or only on Spanish assets and Spanish-source income.
- Non-residents, including UK and US owners of Spanish property, are taxed on wealth only for assets located in Spain and receive the state exempt minimum of €700,000.
- In the Comunitat Valenciana, residents have an exempt minimum of €2,000,000 for wealth held on 31 December 2026 (Ley 5/2026, in force since 11 August 2026), up from €1,000,000 for 2025, but this figure is not available to non-residents.
- The wealth tax return (Modelo 714) follows the income tax campaign: for the 2025 return, the filing period ran from 8 April to 30 June 2026.
- A separate Temporary Solidarity Tax on Large Fortunes applies to net wealth above €3,000,000, has its own filing period starting on 1 July and is prorogued as at 6 October 2026.
Spanish wealth tax and passive income taxation explained
If you live in Spain, plan to move here, or hold Spanish assets, you need to understand how the Spanish wealth tax works alongside the taxation of passive income.
These are separate parts of the system.
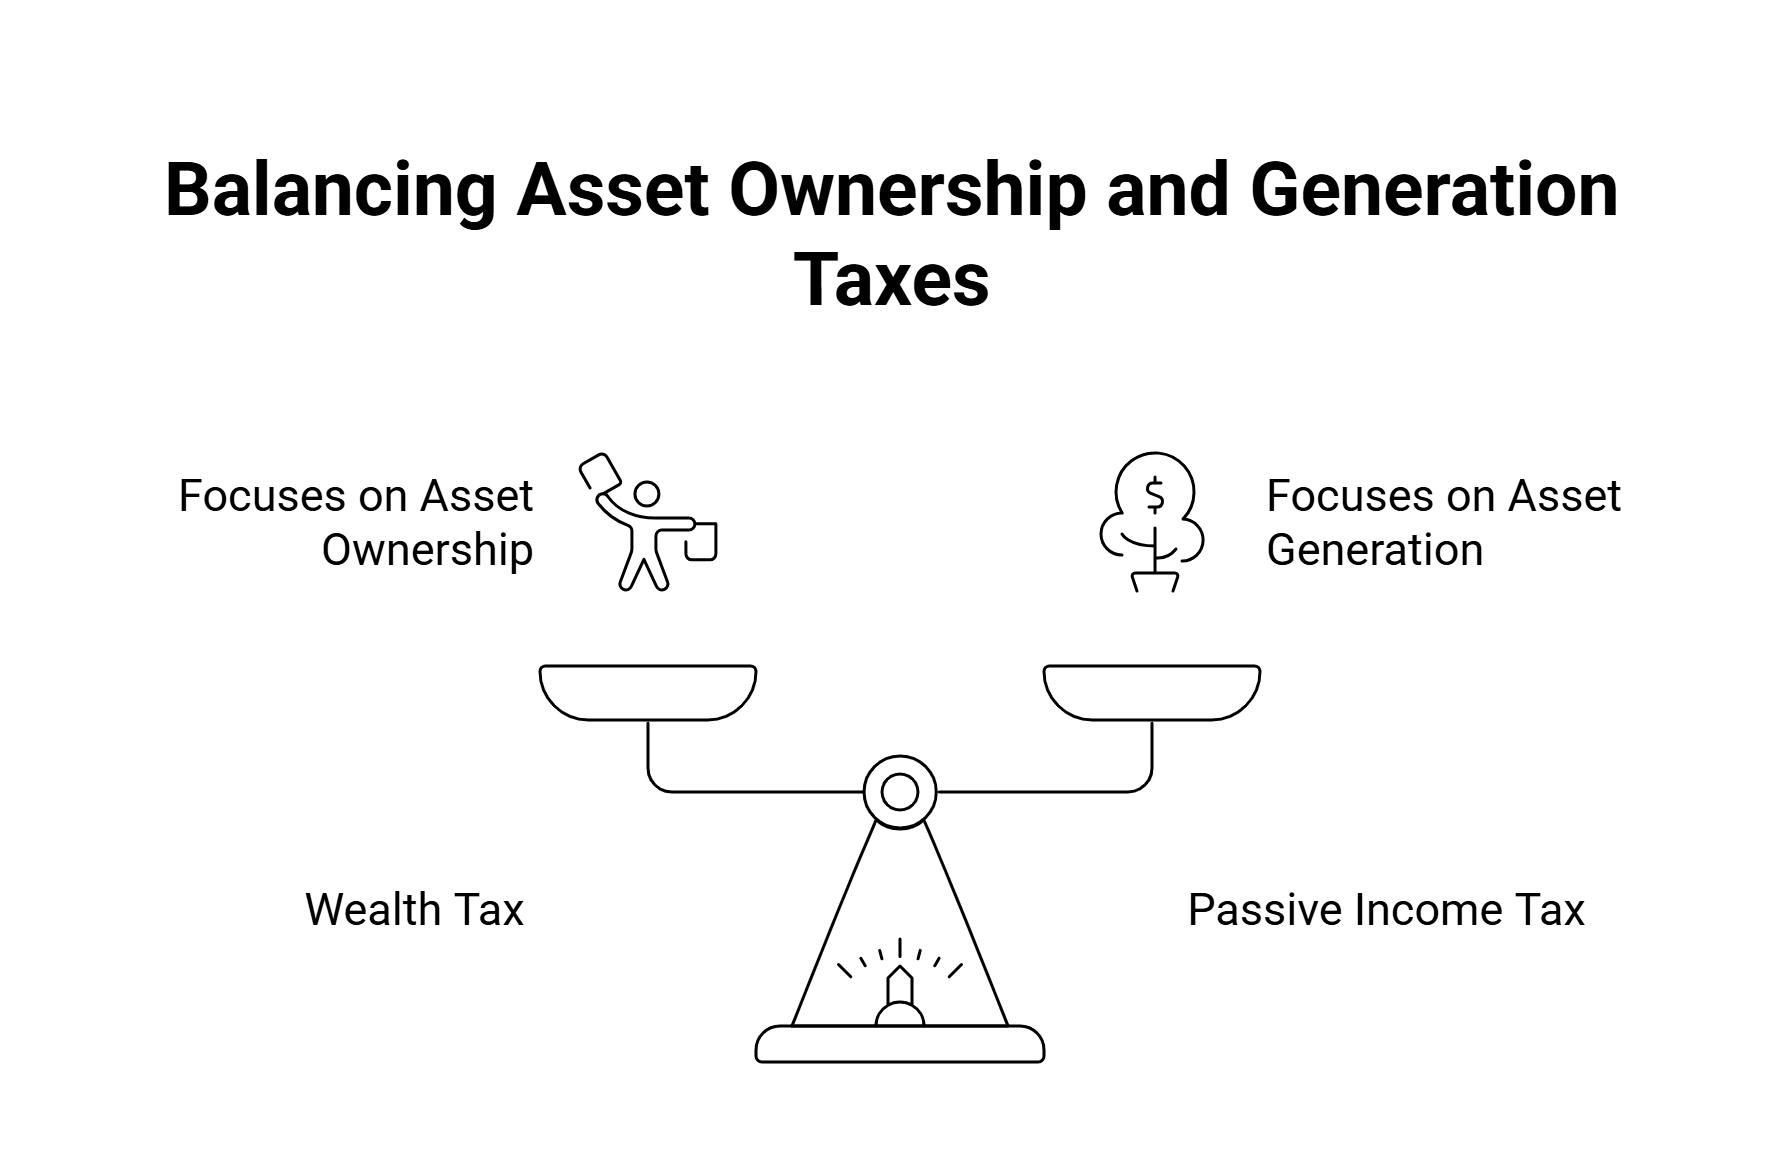
One looks at the value of your net assets on 31 December, while the other taxes what those assets produce during the year, such as interest, dividends, capital gains and rental income.
The rules look simple at first, but the details matter. Spain combines state tax law with regional powers, so your position may depend on whether you are a tax resident, which autonomous community applies to you, and whether your income comes from Spain or abroad. That is why people reviewing their residency in Spain or planning long-term residence in Spain should look at wealth and passive income together rather than in isolation.What is the Spanish wealth tax?
Spanish wealth tax, or Impuesto sobre el Patrimonio, is an annual tax on an individual’s net wealth. Under Law 19/1991 published in the BOE, it is a direct personal tax charged on the net value of assets and rights after deducting debts and liabilities. The tax is assessed by reference to the taxpayer’s position on 31 December each year.Who needs to file?
The Agencia Tributaria page on who must file wealth tax explains that a return is generally required if tax is payable, or if the total value of assets and rights exceeds €2,000,000, even where no final tax is due after exemptions and allowances. The return is filed using Modelo 714.The filing period is the same as for personal income tax and is set each year. For the 2025 return, the AEAT practical manual on wealth tax gives 8 April to 30 June 2026, and a return paid by direct debit had to be filed by 25 June 2026. The Valencian tax agency (ATV) confirms that the same period applies to every wealth tax return, whatever the result.
| Rule | General position |
|---|---|
| Tax residents | Usually taxed on worldwide assets |
| Non-residents | Usually taxed only on Spanish assets |
| General minimum exempt amount | €700,000 for non-residents. Residents get the figure approved by their autonomous community, or €700,000 if it has approved none |
| Main home exemption | Up to €300,000 for the habitual residence of resident taxpayers |
| Annual reference date | 31 December |
| Return form | Modelo 714 |
How the wealth tax rates work
The Spanish wealth tax is progressive. The state scale starts at 0.2% and rises to 3.5%, although autonomous communities can approve their own scales, allowances and rebates. The legal basis sits in the BOE text of Law 19/1991, while the Agencia Tributaria wealth tax section provides the practical filing framework. This regional flexibility is one reason why wealth planning often needs a location-specific review, especially for people buying property or relocating between communities. It also links to wider property planning. Anyone acquiring a home or investment property should consider wealth tax alongside transfer taxes, ownership structure and holding costs.| State scale reference | Marginal rate |
|---|---|
| Lowest bracket | 0.2% |
| Mid-range brackets | 0.3% to 2.1% |
| Top bracket in the state scale | 3.5% |
How passive income is taxed in Spain
Passive income is taxed separately from the Spanish wealth tax. For residents, interest, dividends and most capital gains usually fall into the savings tax base under the Spanish personal income tax rules set out in Law 35/2006 on Personal Income Tax.These percentages are commonly used for savings income bands under the current personal income tax framework.
Residents and non-residents compared
For Spanish residents
- Worldwide assets usually matter for the Spanish wealth tax.
- Interest, dividends and capital gains usually fall into the savings tax base.
- Rental income is usually taxed under resident income tax rules.
For non-residents
- Only assets located in Spain are usually relevant for wealth tax, and the exempt minimum is the state figure of €700,000.
- Dividends and interest are generally taxed at 19%, subject to treaty relief.
- Spanish rental income is taxed at 24% on gross rent, with no deduction of expenses, for residents of the UK, the US and other countries outside the EU and the EEA. Residents of other EU or EEA states that exchange tax information effectively pay 19% and can deduct expenses directly linked to the Spanish income, under articles 24 and 25 of the non-resident income tax law. The AEAT note on the effect of Brexit confirms that 24% applies to UK residents for income accrued from 1 January 2021.
Why regional rules matter
The headline figures are only part of the story. Wealth tax is largely ceded to the autonomous communities, so scales, exemptions and rebates can vary. That means the same portfolio or property position may produce a different result depending on where the taxpayer is resident in Spain. For business owners and internationally structured families, this often overlaps with company ownership, contracts and wider residence planning. In some cases, it is also worth reviewing Spain corporate tax, international contracts in Spain, and how to reduce your tax burden in Spain.Wealth tax in the Valencian Community
This section covers Spanish law and the Valencian angle only. If you also file in the US or the UK, coordinate those filings with your home-country adviser.
The Comunitat Valenciana has raised its exempt minimum twice in two years. The ATV wealth tax page gives €500,000 until 2024, €1,000,000 for 2025 and €2,000,000 from 2026, and the AEAT manual for the 2025 return records the €1,000,000 figure. The €2,000,000 minimum took effect on 11 August 2026 and applies to wealth held on 31 December 2026, which is declared in 2027.
The rule comes from article 19 of Ley 5/2026 (BOE-A-2026-19331), which rewrites article 8 of Ley 13/1997. Its wording is:
«La base imponible de los sujetos pasivos por obligación personal del impuesto que residan habitualmente en la Comunitat Valenciana se reduce, en concepto de mínimo exento, en 2.000.000 euros.»
Who gets the €2,000,000 minimum
The text covers taxpayers who reside habitually in the Comunitat Valenciana. A British or American owner who lives outside Spain does not meet that condition, even if their only Spanish asset is a Valencian property.
For non-residents, article 28 of Law 19/1991 applies the €700,000 state minimum, both to non-residents taxed on a personal basis and to those taxed only on assets in Spain. Non-residents are taxed only on assets and rights located, exercisable or enforceable in Spain, as the ATV page explains.
Non-residents may also apply the rules of the autonomous community where the highest value of their Spanish assets lies (additional provision 4 of Law 19/1991). The AEAT manual states the €700,000 minimum for non-residents, so whether a non-resident can combine the Valencian rules with the €2,000,000 minimum is a point to confirm. Contact us with your facts before you assume a lower or higher figure.
People who move to Spain under the Beckham regime are taxed on wealth only for assets located in Spain, as the AEAT manual explains for taxpayers under article 93 of the personal income tax law. Our guide to the Beckham Law covers who qualifies, and our guide to UK Spain double taxation explains the 183-day rule and residence certificates for British residents.
How Valencia compares with Madrid, Catalonia and Andalusia
The table shows the general exempt minimum for residents in the 2025 return, taken from the AEAT practical manual, with the Valencian figure for 2026. Regional rules change every year, so check the current rules for the year that matters to you.
| Community | General exempt minimum for residents | Basis |
|---|---|---|
| Madrid | €700,000 (no regional minimum is listed, so the state figure applies) | AEAT manual, 2025 return |
| Catalonia | €500,000 | AEAT manual, 2025 return |
| Andalusia | €700,000 (the regional rule only sets higher minimums for taxpayers with a disability) | AEAT manual and article 24 of Ley 5/2021 |
| Comunitat Valenciana | €1,000,000 for 2025 and €2,000,000 for wealth held on 31 December 2026 | ATV, AEAT manual and Ley 5/2026, article 19 |
The minimum is only part of the comparison. The AEAT manual records a general regional bonus of 100% of the wealth tax quota for Madrid and Andalusia, but states that while the Temporary Solidarity Tax on Large Fortunes remains in force that bonus is replaced by a transitional one, calculated as the difference between the two quotas (2025 return). Our guide to Spain’s regional property taxes covers the regional taxes that apply when you buy.
The 60% limit and the Temporary Solidarity Tax on Large Fortunes
Article 31 of Law 19/1991 caps the wealth tax quota together with the income tax quotas at 60% of the sum of the income tax bases, and the reduction cannot exceed 80% of the wealth tax quota. The article is written for taxpayers taxed on their worldwide wealth, so ask us how it applies to a non-resident owner.
Article 3 of Law 38/2022 created a complementary Temporary Solidarity Tax on Large Fortunes, charged on net wealth above €3,000,000 on the same taxpayers as the wealth tax, with a €700,000 exempt minimum. Its application is prorogued while the review of wealth taxation within the regional financing reform is pending, and the AEAT page for the tax states that the filing period starts on 1 July. Taxpayers who are not resident in another EU Member State must appoint a representative resident in Spain before the end of the filing period, which matters for UK and US owners.
Residents who also hold assets abroad should check their reporting duty under the Modelo 720. The position above is as at 6 October 2026. To confirm which minimum, scale and bonus apply to your case, use the contact details in the box below.
Key differences between wealth tax and passive income tax in Spain
The Spanish wealth tax is about what you own. Passive income tax is about what your assets earn. In Spain, both can apply to the same person at the same time, and both are shaped by residency status, source of income and regional rules. For residents, the scope can extend to worldwide wealth and global passive income. For non-residents, Spanish assets and Spanish-source income remain the main focus. The safest approach is to review your position before the end of the tax year, especially if you hold foreign investments, Spanish real estate or income-producing assets. Early planning can make a major difference to compliance, disclosure and overall tax efficiency.Professional legal support for Spanish wealth tax and passive income matters
Contact Delaguía y Luzón today to receive clear, strategic advice on Spanish wealth tax planning, passive income taxation, and cross-border tax compliance in Spain.- Email: felix.delaguia@delaguialuzon.com
- Phone: +34 963 74 16 57
Frequently asked questions
Does the €2,000,000 Valencian exempt minimum apply to a UK or US owner of a Valencian property?
Only if the owner resides habitually in the Comunitat Valenciana. Article 19 of Ley 5/2026 refers to taxpayers «que residan habitualmente en la Comunitat Valenciana», and article 28 of Law 19/1991 applies the €700,000 state minimum to non-residents. Non-residents are taxed only on assets located in Spain. How a non-resident can use the regional rules is a point to confirm for each case, so contact us before filing.
When is the wealth tax return due, and must I file if no tax is payable?
The period follows the income tax campaign and is set each year. For the 2025 return it ran from 8 April to 30 June 2026. The AEAT guidance cited above says a return is required if tax is payable, or if the total value of assets and rights exceeds €2,000,000, even where no tax is due.
Do I also have to file the Temporary Solidarity Tax on Large Fortunes?
It applies only to net wealth above €3,000,000, and it is filed separately from the wealth tax, with a filing period that starts on 1 July. It is prorogued as at 6 October 2026, so check its status for each tax year before you file. If you are not resident in another EU Member State, you must appoint a representative in Spain.